 The Ledford Group
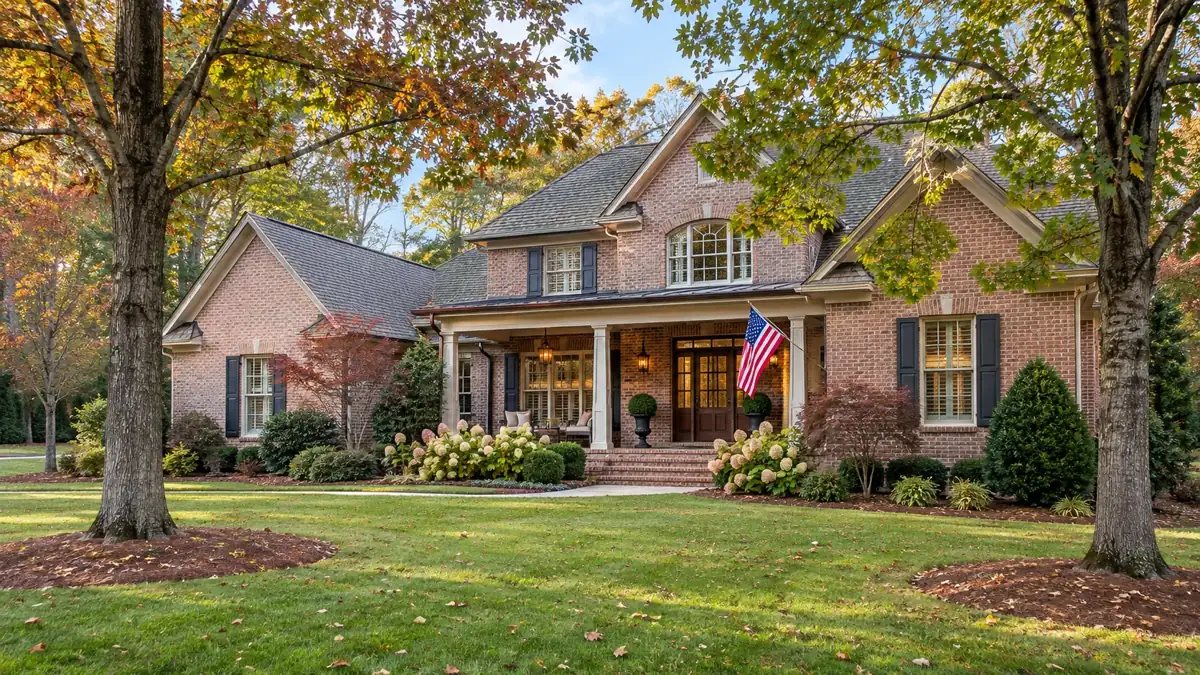
Yes, a VA loan can be used on a $700,000 or higher Marvin, NC home. If you have your full VA entitlement, the VA says there is no loan limit, as long as a lender approves you and the appraisal supports the price. The limits only come into play if you have already used part of your entitlement.
Quick Answer: A veteran with full VA entitlement can buy a $700,000 or higher home in Marvin, NC with a VA loan, because the VA sets no loan limit for full entitlement. The lender still has to approve your income and credit, and the home has to appraise at or above the price. Jennifer Ledford of The Ledford Group by eXp Realty walks Marvin buyers through the VA process, and a VA-experienced lender confirms the final numbers.
Veterans Day is Wednesday, November 11. I don't assume anyone reading this is a veteran. But if you served, or you're married to someone who did, this is one of the most useful pieces of information you can have before you start looking at larger homes.
I'm Jennifer Ledford with The Ledford Group by eXp Realty. Marvin is one of my lead markets, and I want to give you a straight answer on how a VA loan works at Marvin price points. I'm a REALTOR, not a lender, so every rule below should be confirmed with a VA-approved lender before you write an offer.
Is there a limit on a VA loan in Marvin?
It depends on how much of your entitlement is available. Entitlement is the amount the VA promises to guarantee for your lender. Think of it as the VA backing part of your loan, so the lender takes less risk.
According to the VA's loan limits page (last updated August 12, 2025), your basic entitlement covers loans up to $144,000. Above that, the VA guarantees 25 percent of the loan amount. For a veteran with full entitlement, the VA says there is no loan limit, provided the lender approves you and the appraisal supports the price.
That's the part many buyers miss. You may have heard that VA loans top out around a conforming limit. That number matters only when your entitlement has been used, which I'll explain below.
What does "full entitlement" mean?
Full entitlement means you have never used your VA loan benefit, or you used it and paid the loan off and sold the home, which restores it. It also applies in some cases where the earlier loan was paid off and you have kept the home. Your Certificate of Eligibility, called a COE, shows exactly where you stand. A lender can pull it for you, or you can request it through VA.gov.
If you have entitlement tied up in a home you still own with a VA loan, you have what the VA calls remaining entitlement. That's a different calculation.
How do the limits work with remaining entitlement?
With remaining entitlement, the VA says your remaining bonus entitlement equals 25 percent of the county loan limit, minus the entitlement you've already used. The VA states that these limits are the same as the conforming loan limits set by the Federal Housing Finance Agency, and it points buyers to that agency for county figures.
The VA's own example uses a $900,000 county limit and $50,000 of used entitlement. That leaves $175,000 in remaining bonus entitlement. If that doesn't cover 25 percent of the loan, the lender may ask for a down payment to make up the gap. That example is a teaching number, not a Union County figure, so don't use it for your own math.
The takeaway: if you have never used the benefit, you're in the simplest position. If you have, ask your lender to run your remaining entitlement before you shop.
Do I need a down payment on a $700,000 home?
With full entitlement, a VA loan doesn't require one. That's one of the biggest features of the program. You can put zero down on a $700,000 home if the lender approves the loan and the home appraises.
You can still choose to put money down. A bigger down payment lowers the monthly payment and, as you'll see below, lowers the funding fee.
What is the VA funding fee, and how much is it?
The funding fee is a one-time charge, a percentage of the loan amount, that helps keep the VA loan program running. You can pay it at closing or roll it into the loan. The VA's funding fee page (last updated October 5, 2026) lists these rates for a purchase loan for veterans, active-duty members, and National Guard and Reserve members:
First use, less than 5 percent down: 2.15 percent
First use, 5 percent or more down: 1.5 percent
First use, 10 percent or more down: 1.25 percent
After first use, less than 5 percent down: 3.3 percent
After first use, 5 percent or more down: 1.5 percent
After first use, 10 percent or more down: 1.25 percent
The VA's chart is labeled as effective April 7, 2023. Some veterans pay no funding fee. The VA lists exemptions that include veterans who receive VA compensation for a service-connected disability, surviving spouses who receive Dependency and Indemnity Compensation, and active-duty members who show a Purple Heart on or before closing. Ask your lender and check VA.gov to see if you qualify.
What would a $700,000 Marvin home cost me each month?
Here's a simple example so you can see the effect of the funding fee and the down payment. I used 7.18 percent, the Freddie Mac 30-year fixed average from its November 5 release. VA loan rates can be different, so this is only a way to compare the three choices. It covers principal and interest only. Taxes, insurance, and any HOA dues are extra. It's an example, not a quote.
On a $700,000 home, first use of the benefit:
Zero down: the funding fee is 2.15 percent, about $15,050. Rolled into the loan, the balance is about $715,050. Principal and interest is about $4,844 a month.
5 percent down ($35,000): the loan is $665,000. The 1.5 percent fee is about $9,975. Rolled in, the balance is about $674,975. Principal and interest is about $4,573 a month.
10 percent down ($70,000): the loan is $630,000. The 1.25 percent fee is about $7,875. Rolled in, the balance is about $637,875. Principal and interest is about $4,321 a month.
Look at the gap. Between zero down and ten percent down, the payment drops by roughly $523 a month, and the fee drops by about $7,175. Money you put down works twice. It shrinks the loan and it cuts the fee.
That doesn't mean you should drain your savings. I'd rather see you keep a healthy cushion for moving costs and any repairs. Ask your lender to run all three versions so you can see the choice in numbers.
Will a Marvin home appraise for a VA loan?
This is where a VA loan can get tricky, and it's worth planning for. The VA says the maximum loan on a property is the lower of the appraised value or the purchase price. If the home appraises below your contract price, you have a few options. You can ask the seller to lower the price, bring cash to cover the gap, or walk away if your contract allows it.
VA appraisers also check that the home meets the VA's minimum property requirements. That means the home should be safe, sound, and sanitary. In practice, a Marvin home with a failing roof or a broken well pump can slow a deal down.
Marvin homes often sit on large lots with unusual features. Many have wells, septic systems, long driveways, ponds, or outbuildings. Those details can affect an appraisal and a lender's review. I always tell buyers to ask the lender early whether anything about the property could cause a VA issue, before we're deep into the contract.
How competitive is a VA offer in Marvin?
Sellers sometimes worry that a VA loan will bring extra hassle. In my experience, that worry is usually about the appraisal and the repair requests, not the buyer. A VA offer is strong when it's well prepared.
Here's what makes one stand up:
A pre-approval letter from a lender who does VA loans often, with your COE in hand.
A clean offer with realistic terms and a clear timeline.
Pricing discipline. A home that's priced well above what similar homes sold for is the one most likely to appraise low.
A home inspection done early, so any issue shows up before the appraiser arrives.
Under the Committed Client Method, my buyers sign a buyer agency agreement before I open any door. That gives me the standing to negotiate hard on your behalf, including asking the seller to cover a repair the VA requires. I won't promise a seller will agree. I will make sure your offer is built to be taken seriously.
What does living in Marvin look like day to day?
Marvin doesn't have a downtown, and that's by design. Buyers choose it for space and privacy. When you want a grocery run, Stonecrest Shopping Center, anchored by Whole Foods, is about five to ten minutes away. For dinner, many Marvin neighbors head to Postino Ballantyne for wine and small plates, or to 131 MAIN for a special night out.
For a walk, Marvin Efird Park has trails and open green space. If you want a bigger outdoor day, Cane Creek Park in Union County has more than 1,000 acres, with fishing, hiking, and camping about 20 minutes away.
Homes in Marvin generally run from about $600,000 to well over $2 million, so a $700,000 budget puts you in the conversation, not at the top of it. Neighborhoods worth a look at that level include The Preserve at Marvin for established inventory, plus Sage at Marvin and Marvin Commons for newer construction. Prices, lot sizes, and HOA dues change from street to street, so I pull current sold prices before we tour.
For schools, Marvin Elementary, Marvin Ridge Middle, and Marvin Ridge High are the Marvin-area schools I reference. Assignments depend on the address and can change. I never tell a buyer a specific home is assigned to a school until Union County Public Schools confirms it.
What are the first steps if I'm a veteran buying in Marvin?
Here's the order I'd follow:
Get your Certificate of Eligibility, or have a VA lender pull it.
Ask the lender to run your entitlement, whether full or remaining, and a payment at three down payment levels.
Get pre-approved in writing.
Choose an agent who has worked VA deals and will sign a buyer agency agreement with you.
Look at homes with the appraisal and property requirements in mind.
Order the inspection early, and keep the VA timeline in view.
If you'd like me to put together a short list of Marvin homes that match your numbers, call me at 704-607-6996. I'll tell you the truth about what fits and what doesn't, and I'll connect you with lenders who work with VA loans regularly.
Frequently asked questions
Is there a maximum VA loan amount in North Carolina? For a veteran with full entitlement, the VA says there is no loan limit, as long as the lender approves the borrower and the appraisal supports the price. If you have remaining entitlement, county limits apply and the lender may ask for a down payment on the gap. A VA lender can run your exact numbers.
Can I buy a Marvin NC home with no down payment using a VA loan? With full entitlement, a VA loan doesn't require a down payment. The lender still has to approve your income and credit, and the home has to appraise at or above the price. You'll also owe a funding fee unless you're exempt.
How much is the VA funding fee on a first-time VA purchase? For a first use with less than 5 percent down, the VA lists a funding fee of 2.15 percent. It drops to 1.5 percent with 5 percent or more down and 1.25 percent with 10 percent or more down. Veterans who receive VA compensation for a service-connected disability are exempt.
What happens if a Marvin home appraises for less than my VA offer? The VA says the maximum loan is the lower of the appraised value or the purchase price. You can ask the seller to lower the price, bring cash to cover the difference, or end the contract if your terms allow. Your agent can help you plan for this before you make the offer.
About Jennifer Ledford: Jennifer Ledford is a licensed REALTOR with The Ledford Group by eXp Realty, serving buyers and sellers across Mecklenburg, Union, Stanly, and York Counties since 2016. She is among the top 3% of 18,000+ agents in the Charlotte Metro, an eXp ICON, and has guided 250+ clients through some of the most significant transactions of their lives. Reach her at 704-607-6996 or https://the-ledford-group.com.
Jennifer Ledford | 📞 704-607-6996 | 🌐 https://the-ledford-group.com
Updated November 8, 2026. VA entitlement and loan limit details come from the VA's loan limits page (last updated August 12, 2025). Funding fee rates and exemptions come from the VA's funding fee page (last updated October 5, 2026; rate chart effective April 7, 2023). The 7.18% rate is the Freddie Mac 30-year fixed average from November 5, 2026, used only to compare examples. Payment examples are principal and interest only, rounded, and not a quote or financial advice. Confirm all VA rules with VA.gov and a VA-approved lender. Park, shopping, and dining details come from my local notes.
About the author
Jennifer Ledford, REALTOR, has helped Charlotte-area buyers and sellers full time since 2016, with 250+ homes sold. She is a Certified Negotiation Expert with The Ledford Group by eXp Realty.
Book a Call with Jennifer